Jackson Hole Jump For Mortgage Rates
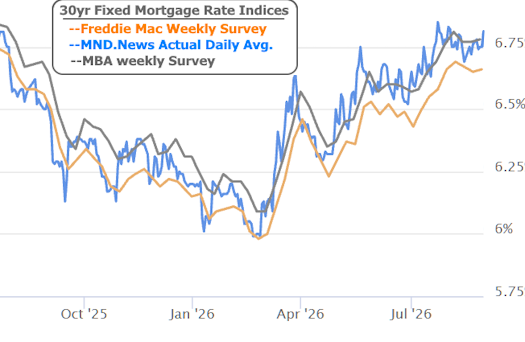
Mortgage rates were on track for a fairly uneventful week until Friday morning, when a speech from Fed Chair Kevin Warsh triggered a sharp bond market sell-off. The average top-tier 30yr fixed rate jumped to its highest level in just over 3 weeks.
The week started with more headlines about Treasury buying back its own bonds. Despite widespread news coverage, buybacks failed to inspire sustained reaction last week, and traders were even less interested this week. At best, buybacks can change the balance between shorter and longer-term yields, but they do not create broad, lasting relief for rates. In practical terms, Monday's modest improvement had much more to do with lower oil prices.
That pattern continued Tuesday as hopes for progress toward a peace deal pushed oil and Treasury yields lower together. Oil has been unusually important for rates because any lasting disruption in the Strait of Hormuz raises concerns about energy costs and inflation.
Wednesday brought July's PCE inflation report, the Fed's preferred measure of inflation. The core reading, which excludes food and energy, matched forecasts when rounded to the nearest tenth of a percent (0.2 vs 0.2). But at an unrounded value of 0.247%, it was virtually as high as possible without rounding up to 0.3. Markets often inspect these unrounded numbers to glean directional cues from otherwise uninspiring data. That exercise added some pressure on rates on Wednesday, but it wasn't the week's biggest story.
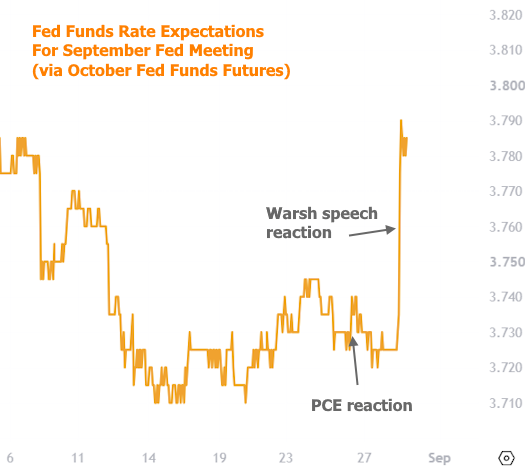
That honor went to Fed Chair Warsh's speech at the Fed's annual Jackson Hole conference. Warsh described the economy and labor market as strong, said the Fed's 2% inflation target was firm and fixed, and noted that present rate levels don't appear to be doing anything to restrain financial conditions.
Markets interpreted the combination as a warning that the Fed is in no hurry to cut rates and may be more willing to raise them again if inflation remains elevated. The following chart shows the changes in the expected Fed Funds Rate at the next Fed meeting in September. In terms of % probability, this represents more than a 50% chance of a rate hike.
It always bears repeating that the Fed does not directly set mortgage rates. But mortgage pricing reacts to the bond market's expectations about what the Fed is likely to do. Short-term Treasury yields rose more than one-tenth of a percentage point after Warsh's speech. Medium term Treasuries (which correlate strongly with the bonds that dictate mortgage rates) felt a good amount of that pressure. The net effect was the sharpest mortgage rate spike in several weeks.
The saving grace is that Friday's average mortgage rates were only modestly higher than those seen last Friday.
Next week brings the glut of top-tier economic data typically seen at the start of the month with the star of the show always being Friday's big jobs report. Weaker employment data could challenge Warsh's upbeat assessment and help rates recover. Stronger data would reinforce Friday's message and could keep rates under pressure. Fuel prices remain the other major wild card.
-
Mortgage rates increased after Fed Chair Kevin Warsh described the economy and labor market as strong, reaffirmed the Fed’s 2% inflation target, and suggested that current rates were not restraining financial conditions.
-
No. The Federal Reserve does not directly set mortgage rates. Mortgage rates respond to bond-market expectations about inflation, the economy, and what the Federal Reserve may do next.
-
Markets interpreted the speech as a sign that the Federal Reserve was not in a hurry to lower rates and might consider raising them if inflation remained elevated.
-
July’s core PCE reading matched forecasts when rounded, but the unrounded figure was close to rounding higher. That detail added some upward pressure to rates on Wednesday.
-
The upcoming jobs report and changes in fuel prices could influence rates. Weaker employment data could help rates recover, while stronger data could keep rates under pressure.