Mountains vs Molehills: What Rates Really Cared About This Week
Mortgage rates ended the week moderately higher, but things could have been slightly worse without Wednesday's surprisingly sharp drop in longer-term Treasury yields (a key benchmark for mortgage rates). The cause was an announcement about Treasury's bond buyback program--a subject that made far more noise than its lasting impact warranted.
The week began with the same market mover we've grown accustomed to since the Iran war: oil. Renewed threats from Iran and the seizure of a UAE tanker in the Strait of Hormuz pushed oil prices and Treasury yields higher on Monday. By Tuesday morning, the 10yr yield briefly touched 4.75%, a level that attracted enough bond buying to help the market stabilize.
Wednesday began with news that Treasury would at least double the maximum size of certain long-term buyback operations, from $2 billion to $4 billion, beginning September 9th. Despite the name, this isn't quantitative easing (QE), and Treasury isn't creating money to force rates lower. It already buys back older, harder-to-trade bonds to improve market liquidity, funding the purchases through its normal cash and borrowing operations.
Investors nevertheless reacted aggressively because the change was focused on Treasury debt maturing in 10 to 30 years. The 30yr yield fell almost one-tenth of a percentage point, while the 2yr yield moved slightly HIGHER (with an "h"). That divergence is the key clue: this was not broad stimulus for rates. Mortgage rates fell as well, but not nearly as much because mortgage-backed bonds typically last only 5 to 7 years as homeowners sell, refinance, or otherwise pay off their loans.
By Thursday, the one-time adjustment had largely run its course. The headlines continued after Treasury Secretary Bessent discussed the program on television, but the actual trading returned to oil prices. Oil jumped overnight, and Treasury yields followed almost perfectly. Elevated corporate bond issuance from hyperscalers added background pressure (an esoteric topic, but suffice it to say that heavy corporate bond issuance coincides with higher rates across the board, all else equal).
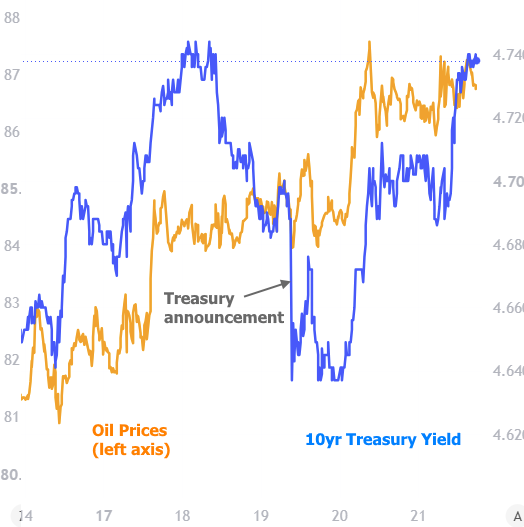
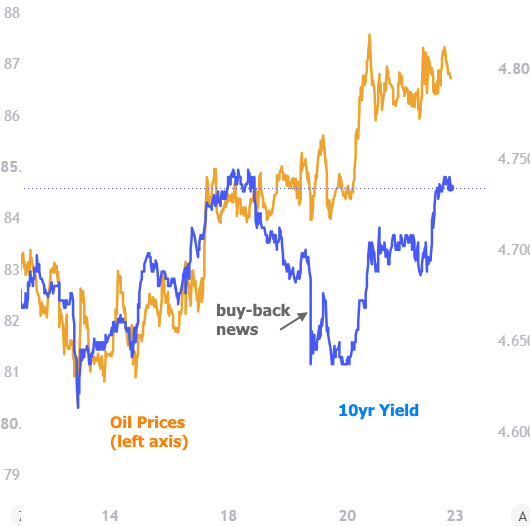
By the end of the week, oil prices were even higher than they were on Tuesday, yet the 10yr Treasury yield remained slightly lower. In that limited sense, Wednesday's announcement provided a reset for longer-term yields. But after that reset, yields continued higher for the same reasons they likely would have risen without the Treasury news--especially oil prices and heavy corporate bond issuance.
The following chart has the same lines as the previous chart, but with different y-axis scaling to highlight Wednesday's "reset" for the bond market.
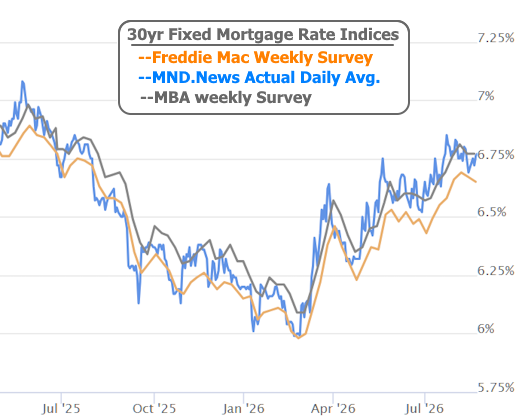
Mortgage rates rebounded to 6.76% on Thursday and 6.77% on Friday, up from 6.69% the previous Friday
Friday offered little new direction, although a modest shift toward higher expected Fed rates added some late pressure. Next week brings a much busier economic calendar and the Fed's annual Jackson Hole conference, including comments from Fed Chair Warsh. Those events should give the market something more substantial than this week's buyback melodrama.
-
The article identifies the upcoming economic reports and the Federal Reserve’s annual Jackson Hole conference as potential market-moving events. Comments from Fed Chair Warsh could also affect rate expectations.
-
Mortgage rates initially moved lower after the announcement, but not as sharply as longer-term Treasury yields. By Thursday, the initial market adjustment had largely run its course.
-
The program allows the Treasury to purchase older, less actively traded bonds to improve market liquidity. The purchases are funded through the Treasury’s normal cash and borrowing operations.
-
Renewed threats from Iran and the seizure of a tanker in the Strait of Hormuz pushed oil prices higher. Treasury yields generally followed oil prices, contributing to higher mortgage rates.
-
Mortgage rates moved moderately higher as rising oil prices, heavy corporate bond issuance, and slightly higher expectations for future Federal Reserve rates placed pressure on the bond market.